Saving money sounds simple until real life gets in the way. A surprise car repair, a holiday sale, a week of expensive takeout — and suddenly your good intentions vanish. That is exactly why a savings tracker works: it turns a vague goal into something you see, measure, and celebrate every single day. In this 2026 guide, you will learn how to set up a savings tracker, which savings goals to track first, and the habits that turn tracking into real money in the bank.
What Is a Savings Tracker and Why It Works
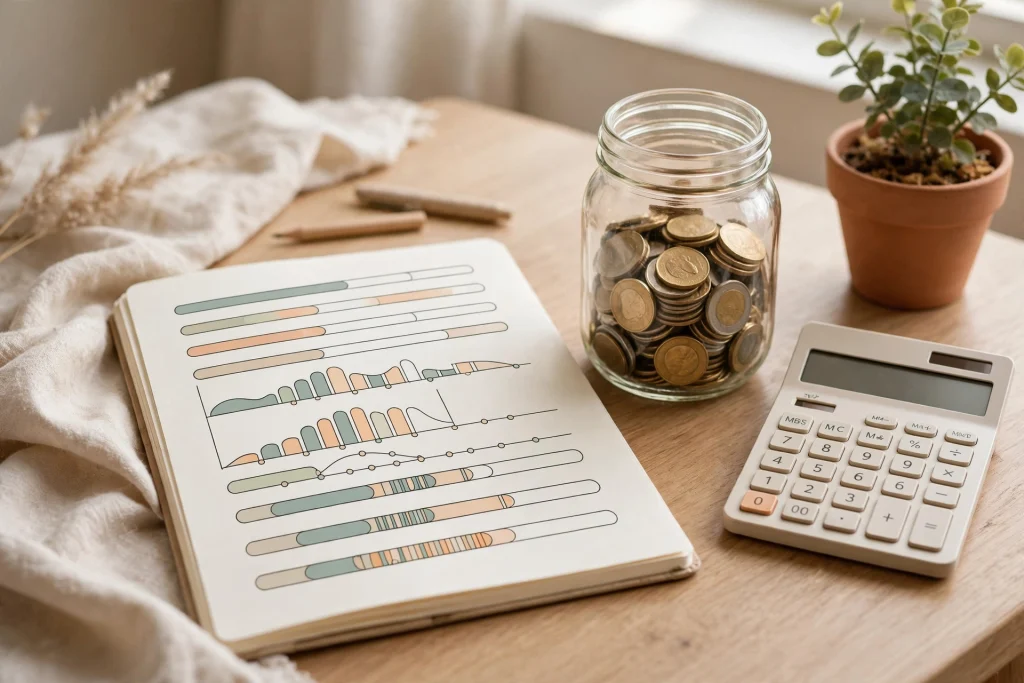
A savings tracker is a dedicated log — digital or printable — where you record every deposit toward a savings goal and watch the balance grow toward your target. It can be as simple as a one-page chart you color in, or a full digital planner spread with monthly progress bars, charts, and goal check-ins.
Why does something so simple work so well? Behavioral research points to three mechanisms:
- Visibility: When your progress is one tap away, saving stays top of mind instead of buried in a bank app you open twice a month.
- The completion effect: Coloring in a box, checking a milestone, or watching a bar fill creates a small dopamine hit that reinforces the saving habit.
- Honest feedback: A tracker shows exactly what you saved — not what you planned to save. That honesty is what closes the gap between intention and action.
Plenty of people set savings goals in January and forget them by March. A savings tracker is the difference between a goal you wish for and a goal you watch grow.
How to Set Up Your Savings Tracker in 7 Steps
You do not need a complicated system to start. Follow these seven steps and your savings tracker will be running in under an hour.
Step 1: Name your savings goal
Vague goals die quietly. “Save more money” means nothing to your brain, but “Save $5,000 for an emergency fund by December 2026” gives you a number and a deadline. Write the exact target amount and the date you want to reach it.
Step 2: Break the goal into monthly (and weekly) chunks
Divide your total target by the number of months left. A $5,000 goal over 10 months means $500 per month, or about $125 per week. Weekly targets feel more achievable and give you faster feedback loops, which keeps motivation high.
Step 3: Choose your tracker format
A digital savings tracker inside a planner app like GoodNotes keeps everything in one place: your budget, your expenses, and your savings progress side by side. A digital finance planner with a dedicated savings journal is ideal because your goal tracker, expense log, and monthly budget reviews live together — you can see instantly how spending decisions affect your savings. Printable trackers work too if you prefer pen and paper.
Step 4: Build in automation first
The most reliable savings are the ones you never have to decide about. Set up an automatic transfer on payday — even a small one — into a separate savings account. Your tracker then records what automation already did, plus any extra manual deposits you add during the month.
Step 5: Add a visual progress element
Humans are wired for visuals. Add a progress bar, a thermometer chart, or a grid of boxes to color in as you hit milestones. If your goal is $5,000 and you track in $100 boxes, each colored box is a small win worth noticing.
Step 6: Schedule a weekly money date
Set a recurring 15-minute appointment with yourself — Sunday evening works for most people — to update your savings tracker, log deposits, and review the week ahead. Consistency matters more than perfection; a quick weekly check-in beats a monthly overhaul.
Step 7: Review and adjust monthly
At the end of each month, compare your target against reality. Did you overshoot? Great — raise next month’s target slightly. Did you fall short? Adjust without guilt. A savings tracker is a navigation tool, not a report card.
Savings Goals Worth Tracking First
Not all savings goals are equal. If you are tracking multiple goals, prioritize in this order:
1. Emergency fund
An emergency fund of three to six months of essential expenses is the foundation of financial stability. It turns crises into inconveniences. Track it as your number-one savings goal, and resist the urge to raid it for non-emergencies. This is the goal that matters most in 2026, with living costs still unpredictable.
2. Sinking funds
Sinking funds are mini-savings for predictable-but-irregular expenses: car insurance, holiday gifts, annual subscriptions, vet bills. Instead of being blindsided twice a year, you save a small amount monthly toward each one. Track each sinking fund as its own line in your savings tracker so you always know what is covered.
3. Big purchases
A vacation, a new laptop, furniture — tracking a big purchase keeps you from financing it on credit. Set the price, the deadline, and watch the bar fill. When the goal is fully funded, buying it feels like a reward, not a risk.
Savings Challenges That Actually Work
Savings challenges add structure and gamification to your savings tracker. Here are the ones with the best track record:
- 52-week challenge: Save $1 in week one, $2 in week two, and so on. By week 52 you will have saved $1,378. Reverse it (start at $52) if big early wins motivate you more.
- 100-envelope challenge: Number 100 envelopes from 1 to 100, draw one each day, and put that dollar amount inside. You will save $5,050 in 100 days. A printable version — like these cash placeholders and savings slips — makes the daily ritual satisfying and tactile.
- No-spend days: Mark specific days on your tracker where you spend nothing beyond essentials. Ten no-spend days a month can redirect hundreds of dollars toward savings without feeling like deprivation.
- Round-up saving: Round every purchase up to the nearest dollar or five dollars and save the difference. It is painless because each amount is tiny — but over a month it adds up.
7 Habits That Supercharge Your Savings Tracker
- Track before you spend, not after: Glance at your savings tracker before a discretionary purchase. The visual reminder often changes the decision.
- Save on payday: Move money to savings the day income arrives, not at the end of the month when there is nothing left.
- Name your accounts: “Emergency Fund” and “Japan Trip 2026” are harder to raid than “Savings Account #2.”
- Celebrate milestones publicly: Telling a friend or partner when you hit 25%, 50%, and 75% creates accountability.
- Pair it with expense tracking: Your savings tracker shows deposits; an expense log shows leaks. Use both together — a full digital life planner with budgeting and journaling keeps your whole money picture in one dashboard.
- Keep a “why” list: On the first page of your tracker, write three reasons you are saving. Read them when motivation dips.
- Forgive and resume: One bad week does not erase six good ones. Log the miss honestly and keep going — streaks matter less than totals.
Common Savings Tracker Mistakes to Avoid
- Tracking too many goals at once: Three active savings goals is the practical maximum. More than that and your attention — and your money — fragments.
- Never reconciling with your bank: Your tracker should match your actual account balance at least monthly. Drift destroys trust in the system.
- Setting the bar impossibly high: A target that requires zero spending on joy will collapse by February. Build small pleasures into the budget.
- Hiding the tracker in a forgotten app: If updating it takes more than two minutes, you will stop. Keep it on your planner’s home screen or your most-used notebook.
Frequently Asked Questions
How much of my income should I save each month?
A common general guideline is the 50/30/20 rule: roughly 50% of after-tax income for needs, 30% for wants, and 20% for savings and debt payoff. If 20% is not realistic right now, start with whatever you can — 5% tracked consistently beats 20% planned but never executed. Increase the percentage whenever your income rises.
Should I use a digital or paper savings tracker?
Both work; the best one is the one you will actually update. Digital trackers shine for automatic calculations, charts, and keeping your budget, expenses, and savings in one place. Paper trackers are unbeatable for the tactile satisfaction of coloring in progress. Many people use both: a digital planner for the numbers and a printable chart on the fridge for motivation.
What is the difference between a savings tracker and a budget?
A budget plans where your money goes; a savings tracker measures progress toward a specific goal. They complement each other: your budget decides how much to save each month, and your tracker confirms it happened and shows how close you are to the finish line.
How do I stay motivated when saving feels slow?
Shrink the feedback loop. Track weekly instead of monthly, use small visual milestones, and celebrate each one. Also revisit your “why” list regularly — connecting deposits to a concrete future (security, a trip, a home) keeps the habit meaningful when the numbers grow slowly.
Can a savings tracker help me pay off debt too?
Yes — the same mechanics apply. Track your debt balance decreasing instead of savings increasing. Many people track a debt payoff goal and an emergency fund side by side, splitting extra money between the two. The visual progress works identically in both directions.
Starting a savings tracker in 2026 is one of the highest-leverage money habits you can build: it costs nothing, takes minutes a week, and turns saving from a wish into a visible, growing reality. Set your goal, automate what you can, and update your tracker every week — your future self will thank you. Ready to get organized? Browse our digital planner collection and find the perfect savings tracker setup for your goals.
Temply Studio
Stop chasing your goals with sticky notes and scattered notebooks. Our premium digital planners and Canva templates are designed to help you plan with intention, stay consistent, and actually enjoy the process.
Questions about this guide?
Ask about the planner, share how you use it, or tell us what to cover next. Your email stays private.